
India’s Tyre Market Isn’t Hard to Enter—It’s Hard to Control
India is one of the world’s largest tyre markets. Demand is steady, replacement cycles are predictable, and vehicle ownership continues to rise across Tier 2, 3, and 4 regions. Yet despite these fundamentals, most tyre brands struggle with uneven growth, weak retail penetration, and low visibility beyond their top distributors.
Thank you for reading this post, don't forget to subscribe!The core issue isn’t manufacturing capacity or brand awareness.
It’s Go-To-Market execution at the retail layer.
Tyres are sold in a hyper-fragmented ecosystem—highway shops, multi-brand dealers, puncture stores, service centres, and rural mechanics. In such a market, scale doesn’t come from campaigns; it comes from coverage discipline.
1. The Indian Tyre Market: Stable Demand, Unstable Execution
1.1 Replacement Market Dominance
Over 65% of tyre demand in India comes from replacements. This means:
- Sales are driven locally, not centrally
- Retailers and mechanics influence brand choice
- Availability beats advertising at the point of sale
Yet many brands still design GTM strategies as if tyres are FMCG products—top-down, distributor-led, and city-centric.
1.2 Multi-Brand Reality at Retail
A typical tyre retailer:
- Stocks 5–8 competing brands
- Switches recommendations based on margin, availability, and relationship
- Rarely has formal brand loyalty
This creates constant churn risk unless brands stay operationally present.
1.3 Rural and Highway Demand Is Underserved
While urban markets are crowded, highway corridors, transport hubs, and rural mobility zones remain under-mapped. These areas:
- Have high wear-and-tear demand
- Offer repeat commercial vehicle business
- Are often invisible to corporate sales dashboards
2. Why Tyre Brands Fail to Scale Consistently
Let’s strip away the excuses.
2.1 Distributor-Led Expansion Has Hit Its Ceiling
Distributors prioritize:
- Fast-moving SKUs
- Known retailers
- Credit-safe relationships
They avoid:
- New retailer onboarding
- Cold outreach
- Market discovery
As a result, entire pockets within the same district remain untouched, even after years of presence.
2.2 No Ground-Level Market Intelligence
Most tyre companies cannot answer:
- How many tyre retailers exist in District X?
- Which retailers sell competitor brands but not ours?
- What is the true sales potential of a taluka or highway stretch?
Without this data, expansion decisions are assumptions disguised as strategy.
2.3 Sales Teams Are Overstretched and Under-Supported
Field sales teams:
- Cover too many retailers
- Spend time firefighting logistics issues
- Rarely focus on new outlet activation
Execution becomes reactive, not strategic.
3. GTM Reality Check: Tyres Are a Retail Infrastructure Problem
Tyre GTM success depends on systematic retail infrastructure, not heroic sales effort.
Winning brands treat GTM as:
- A repeatable process
- A data asset
- A long-term capability
This is where Anaxee’s FMCG-inspired, field-first GTM model becomes relevant for the tyre industry.
4. The Field-First GTM Framework for Tyre Brands
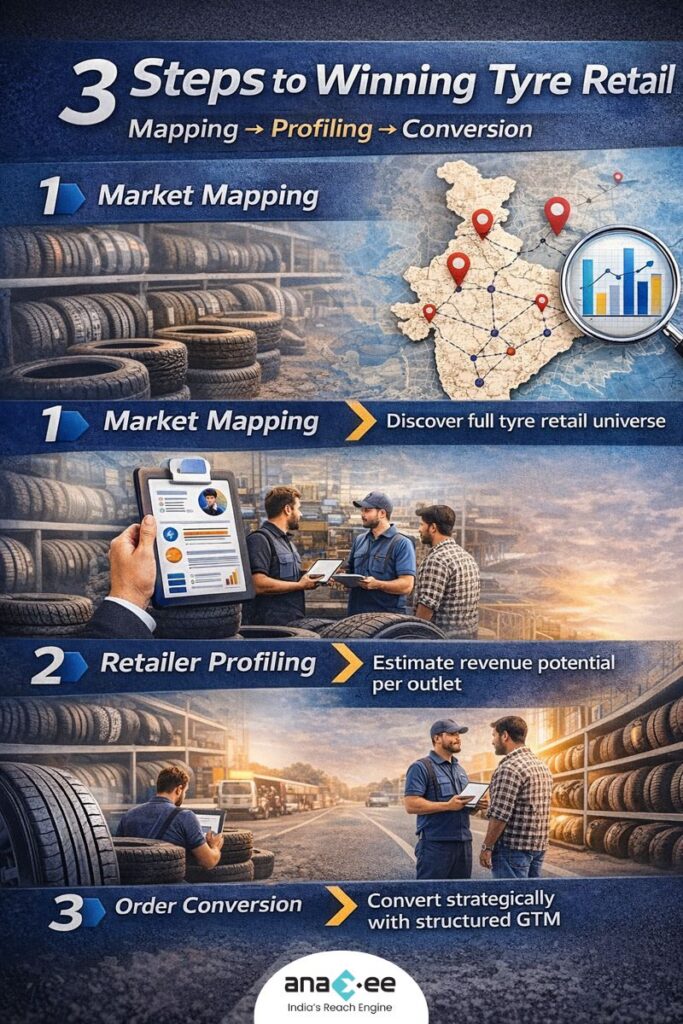
Step 1: Market Mapping — Build the Real Retail Universe
Objective: Discover every tyre-selling outlet—not just the known ones.
On-ground execution includes:
- Mapping tyre shops, puncture stores, mechanics, transport hubs
- GPS tagging and photographic validation
- Classification by outlet type and potential
Insight:
Most tyre brands discover 25–40% more retailers than their internal records show.

Step 2: Retailer Profiling — Separate Volume from Noise
Not all retailers deserve equal effort.
Profiling captures:
- Brands stocked and preferred
- Vehicle segments served (2W, 4W, CV)
- Monthly tyre movement
- Price sensitivity and margin expectations
This enables:
- Outlet-level revenue forecasting
- Smarter incentive allocation
- Strategic SKU placement
Step 3: Structured Activation and Order Taking
Instead of sporadic visits:
- Field teams follow a defined visitation cadence
- Pitches are tailored to retailer profile
- Orders are digitally tracked at SKU level
This creates:
- Consistent brand recall
- Predictable conversions
- Measurable GTM ROI
5. Why This Model Beats Traditional Tyre Sales Structures
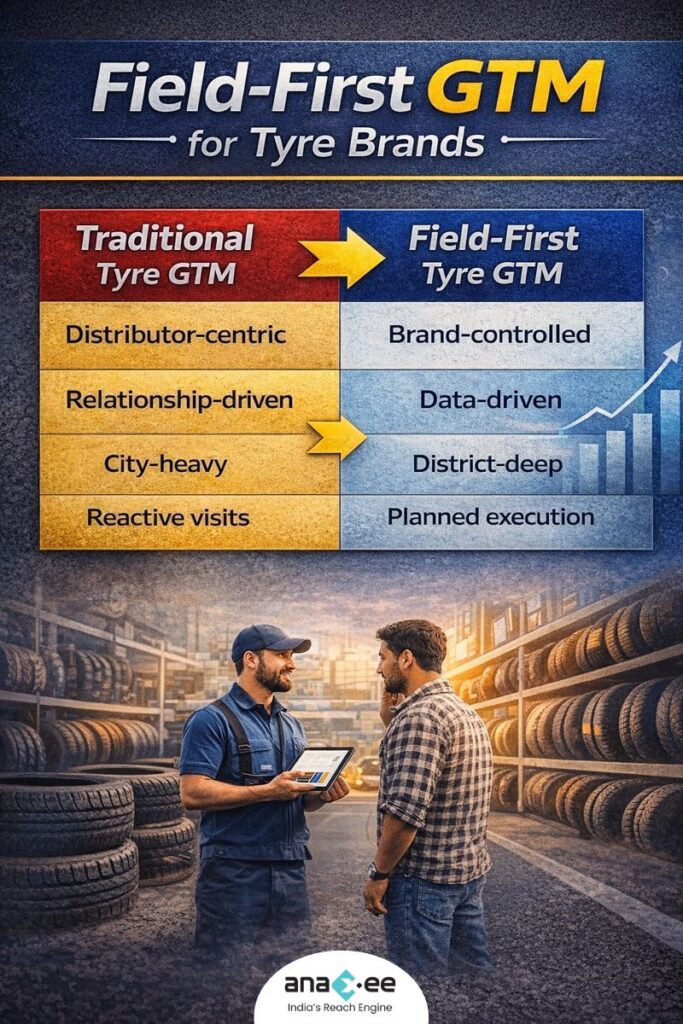
| Traditional Tyre GTM | Field-First GTM |
|---|---|
| Distributor-centric | Brand-controlled |
| Relationship-driven | Data-driven |
| City-heavy | District-deep |
| Reactive visits | Planned execution |
| Low visibility | Full-funnel analytics |
6. What CMOs, CEOs, and Sales Heads Should Care About
6.1 Visibility Replaces Guesswork
You finally know:
- Where growth is stuck
- Where competitors dominate
- Where expansion will actually pay off
6.2 Faster Market Penetration
With mapped and profiled retailers:
- New launches scale faster
- Trade schemes hit the right outlets
- Sales cycles shorten
6.3 Reduced Dependence on Individuals
When GTM becomes system-led:
- Distributor churn hurts less
- Sales attrition doesn’t paralyse growth
- Execution continuity improves
7. Growth Levers Tyre Brands Must Pull by 2026
Winning tyre brands will:
- Invest in district-level retail intelligence
- Build highway and rural coverage early
- Measure success by outlet penetration, not distributor billing
- Treat GTM as a permanent capability, not a project
Frequently asked questions: tyre industry GTM in India
Why do tyre brands struggle to scale despite stable demand?
Because the bottleneck is retail execution, not demand or manufacturing. Over 65% of tyre demand in India is replacement-driven, where local retailers and mechanics decide the brand at the point of sale. Distributor-led, city-centric GTM leaves entire district pockets untouched and invisible to HQ dashboards.
How much of the tyre market is driven by retail and mechanics?
The majority. With ~65% of demand coming from replacements and a typical retailer stocking 5–8 competing brands with little formal loyalty, availability and the retailer’s recommendation beat advertising — so operational presence is what holds share.
What is a field-first GTM strategy for tyre brands?
A systematic model: map every tyre-selling outlet (shops, puncture stores, mechanics, transport hubs — GPS-tagged and photo-validated), profile each by brands stocked and volume, then activate on a planned visitation cadence with SKU-level digital order tracking — turning GTM into a repeatable data asset rather than heroic sales effort.
How many tyre retailers do brands typically miss?
On-ground mapping usually discovers 25–40% more retailers than a brand’s internal records show — especially across highway corridors, transport hubs and rural mobility zones that distributor networks never reach.
Does this apply to other automotive categories?
Yes. The same field-first approach drives growth across the aftermarket — see our companion guide on automotive lubricants GTM in India, and the broader Anaxee Go-To-Market approach.
Conclusion:
Tyre Brands Don’t Lose Market Share—They Fail to Reach It
In the tyre industry, what you don’t see is what defeats you.
Brands don’t lose because competitors are better.
They lose because competitors are present where they are not.
A field-first, data-backed GTM approach gives tyre brands:
- Market clarity
- Execution control
- Scalable growth
In a fragmented aftermarket, distribution discipline is strategy.
Explore how Anaxee enables smarter field execution for you at anaxee.com
 About Anaxee
- ★ National Startup Award 2021
- Trusted by 350+ brands
- India’s Reach Engine since 2016
Explore Anaxee: Go-To-Market · Field data collection · Platform & API · Drone & MRV · Climate
Planning field execution, a GTM rollout or data collection across India?
Tell Anaxee the outcome and the geography — our team will map it across 540 districts and 11,000+ pincodes.
Book a meeting WhatsApp Email salesDistributor Connect: the right distributor for every district
Brands opening new districts can now register where they need distributors, and local businessmen register where they want a distributorship. Our team matches the two. Free for businessmen; the first 25 matched leads are free for brands. 21 categories, all 786 districts, Hindi and English.
Find distributorsBecome a distributorAbout Distributor Connect